What is the baseline valuation and strategic scope of the Defense Tactical Communication Market?
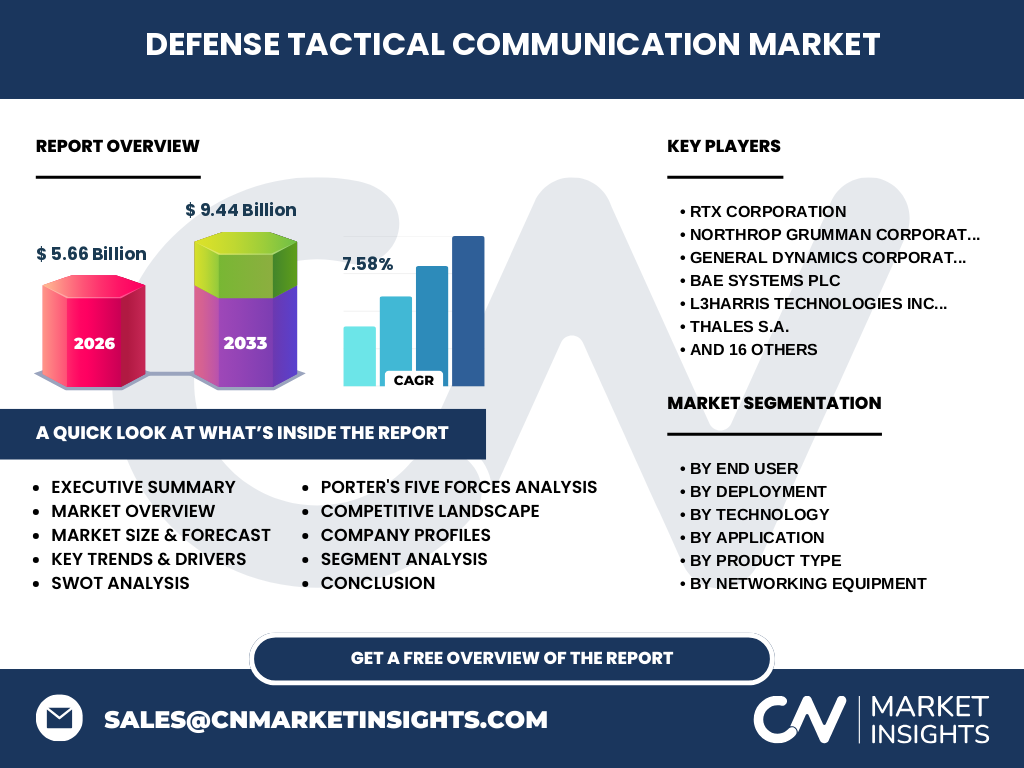
Our analysis indicates that the Defense Tactical Communication Market stands at a robust $5.66 Billion in 2026, serving as the critical nervous system for modern multi-domain operations. This proprietary valuation encompasses secure hardware, tactical internet protocol networks, and cryptographic systems governed by strict regulatory bodies like the Department of Defense and NATO standards, ensuring uninterrupted connectivity amid severe electronic warfare constraints.
Structural Growth Drivers and Operational Restraints in the Defense Tactical Communication Market
The market is propelled by surging demand for real-time battlefield situational awareness, yet faces severe supply chain hurdles regarding gallium arsenide and rare earth minerals critical for radio components. L3Harris Technologies Inc. and General Dynamics Corporation navigate these logistical bottlenecks by securing domestic semiconductor fabrication pipelines, mitigating component scarcity while addressing stringent TEMPEST emission security requirements.
The Shift Toward Resilient Mesh Networks and Tactical Internet Protocols
Industry trends reveal a definitive migration from legacy point-to-point analog links toward decentralized Mesh Networks and Tactical Internet Protocol Networks. This technological pivot enhances survivability in GPS-denied environments. Innovators like RTX Corporation and Viasat are heavily capitalizing on this shift, deploying resilient waveforms that guarantee uninterrupted data flow across mobile and airborne platforms.
Assessing the Post-COVID-19 Recovery Trajectory and Supply Chain Resilience
The pandemic severely disrupted semiconductor sourcing and delayed avionics testing cycles across prime contractors. However, our research confirms a sharp post-COVID-19 rebound fueled by accelerated military modernization budgets. Defense electronics leaders restructured their logistics networks, diversifying tier-two suppliers across allied nations to insulate critical production lines for software-defined radios against future global shocks.
Competitive Benchmarking and Market Concentration in Tactical Communications
The Defense Tactical Communication Market industry trends highlight moderate market concentration, dominated by prime contractors alongside specialized niche innovators. Titans such as Northrop Grumman Corporation and BAE Systems plc leverage massive R&D budgets for enterprise-level command architectures, whereas agile specialists like INVISIO AB and CEOTRONICS AG capture high-margin segments via specialized tactical headsets and intercom systems.
Executive Summary: Key Findings and Valuation Outlook
Our comprehensive evaluation projects the Defense Tactical Communication Market market size to expand from $5.66 Billion in 2026 to $9.44 Billion by 2033, achieving a notable 7.58% CAGR. Strategic investments in Multiple Input Multiple Output Technology and advanced encryption devices will remain the primary value creators for stakeholders throughout this forecast period.
Long-Term Market Forecast and Compound Annual Growth Dynamics
Driven by escalating geopolitical tensions and mandatory digital transformation initiatives across allied armed forces, the market trajectory charts steady upward momentum through 2033. The projected 7.58% CAGR reflects sustained budgetary allocations toward secure tactical data links and airborne satellite communication systems, shifting procurement priorities from hardware replenishment to software-driven interoperability upgrades.
Segmentation Analysis Across End-User, Deployment, Technology, Application, and Product Categories
Our taxonomy segments the ecosystem by End User (Army, Navy, Air Force, Special Forces, Homeland Security), Deployment (Fixed, Mobile, Portable, Wearable), Technology (Tactical IPs, Mesh, MIMO, Encryption), Application (C2, Surveillance, Battlefield Comms), and Product Type (Radio, Satellite, Data, Networking Equipment). Each tier dictates specific procurement cycles, with Special Forces favoring wearable encryption devices and Army deployments prioritizing vehicular-mounted radios.
Geographic Distribution and Regional Performance Hierarchies
Regional performance is heavily skewed toward North America due to extensive defense modernization outlays, followed by rapidly expanding modernization programs across the Asia-Pacific region. Localized regulatory constraints, such as ITAR restrictions in the US and stringent export controls within the European Union, dictate how transnational defense conglomerates like Thales S.A. and Leonardo S.p.A. structure joint ventures and technology transfers.
In-Depth Regional Review of High-Growth Defense Corridors
North America retains the dominant market share, underpinned by continuous Joint All-Domain Command and Control (JADC2) network investments. Meanwhile, the Asia-Pacific theater exhibits the fastest growth rate, driven by border security upgrades and maritime domain awareness initiatives. European allies, influenced by regional defense pacts, are aggressively updating their tactical data links to achieve seamless cross-border interoperability with Saab AB and Kongsberg Gruppen ASA hardware.
Strategic Positioning of Leading Industry Participants
Market leaders utilize distinct competitive strategies to capture recurring government procurement contracts. Elbit Systems and Rohde & Schwarz GmbH & Co. KG focus on modular software-defined radios that offer field-upgradeable waveforms. Meanwhile, companies like Motorola Solutions and Codan Limited leverage commercial-off-the-shelf integration expertise to deliver cost-effective tactical solutions for homeland security and border patrol agencies.
Porter's Five Forces Analysis of the Defense Communications Sector
Bargaining power of buyers is intensely high due to centralized military procurement agencies dictating strict technical specifications and pricing caps. Conversely, threat of new entrants remains remarkably low, constrained by prohibitive R&D costs, stringent accreditation hurdles with bodies like the NSA, and entrenched supplier relationships held by incumbents like Rafael and Icom Incorporated.
SWOT Analysis of the Global Defense Tactical Communication Ecosystem
Key strengths lie in unmatched encryption security and robust mesh networking capabilities. Weaknesses involve vulnerability to advanced electronic jamming and complex supply chains. Opportunities abound in integration with AI-driven decision support tools. Threats stem from sophisticated cyber-attacks targeting tactical routers and network management systems developed by adversaries.
Value Chain Analysis: From Raw Materials to End-User Deployment
The value chain initiates with raw material extraction—specifically rare earth elements and semiconductor-grade silicon—processed by tier-three chemical suppliers. Tier-two vendors fabricate specialized RF components and tactical routers. Prime contractors assemble these into comprehensive command and control data systems, ultimately delivering deployable assets to end-users like the Navy, Army, and specialized tactical units.
Strategic Investment Insights and High-Potential Opportunity Zones
Our research identifies secure wireless data communication systems and tactical network management software as prime investment hotspots. Venture capital and defense primes should target agile innovators specializing in anti-jamming waveforms and quantum-resistant encryption devices, as these technologies represent the definitive future-proofing vectors for the Defense Tactical Communication Market analysis.
Conclusion and Definitive Industry Takeaways
The trajectory through 2033 solidifies this market as a cornerstone of modern national security infrastructure. Reaching $9.44 Billion requires continuous innovation in resilient, multi-domain networking equipment. Enterprises that successfully integrate artificial intelligence with legacy radio architectures will capture outsized market share and redefine tactical superiority.
Research Methodology and Triangulation Framework
Baseline market estimates are rigorously triangulated by synthesizing primary stakeholder interviews with defense procurement officers, exhaustive trade registry data, and secondary macroeconomic indicators. Our analysts cross-reference corporate earnings reports from key entities like Hytera Communications Corporation Limited and Radmor S.A. against official government defense budgets to ensure absolute numerical precision.
Scope of the Report, Coverage Parameters, and Analytical Limitations
This report covers global deployment models across fixed, mobile, portable, and wearable segments, alongside all major product and technology tiers through 2033. Limitations include the exclusion of classified black-budget defense programs and unverified proprietary research from non-reporting private entities, ensuring our data remains rooted in verifiable, transparent industry metrics.
Recent Developments: Strategic Partnerships, Product Launches, and Mergers
Recent industry momentum is defined by strategic joint ventures aimed at bridging disparate tactical internet protocol networks. Firms such as Rapid Mobile (Pty) Ltd. and Savox Communications Oy Ab have rolled out advanced interoperability gateways designed to link legacy manpack radios with modern soldier-worn digital systems, drastically reducing communication friction in coalition operations.